
Rehab Loans in Naples, FL
A renovation mortgage can finance a home purchase and eligible repairs in one loan. Buyers typically need an approved scope of work, cost estimates and a plan for inspections before renovation funds are released.
Loan availability and terms depend on borrower and property qualifications.
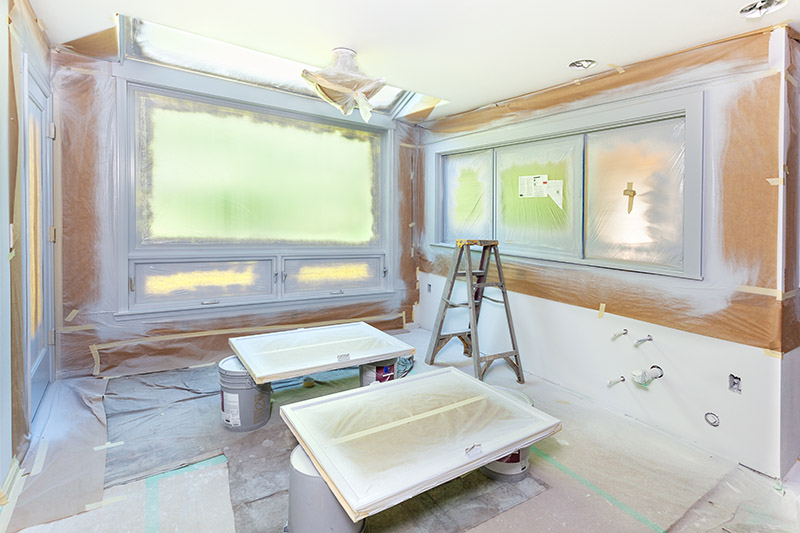
Start with the life you want to build.
See the home. Plan the improvements.
A renovation project needs a financing plan that accounts for the work as well as the property.
A rehab loan is a single mortgage that covers both the purchase or refinance of an existing home and the cost of approved repairs or improvements, based on what the home will be worth after the work. For homeowners and buyers looking at older or storm-worn homes in Naples, FL, First Premier Mortgage (NMLS #2668389) helps you scope the work, compare renovation programs, and organize the contractor paperwork lenders require.
Key Takeaways
- One loan, two jobs The home and the renovation are financed together, so you do not need a separate personal loan or credit card for the work.
- Value after improvements The appraisal estimates the home’s value once the approved work is finished.
- Several program types Government-backed options such as FHA 203(k) and conventional renovation loans have different rules on scope, occupancy and property type.
- Work funds sit in escrow Renovation money is held after closing and paid to the contractor as work is inspected.
- Contractors are part of the file Bids, licenses and insurance are reviewed before closing, and most programs do not allow do-it-yourself labor.
- Plan for a longer timeline Bids, a renovation-based appraisal and project review usually add time compared with a standard purchase.
Common Questions About Rehab Loans
Borrowers usually ask what counts as eligible work, how contractors get paid, and how a rehab loan compares with paying for repairs later. These answers focus on homes you will live in.
What kinds of work can a renovation loan cover?
Roofs, windows, kitchens, baths, flooring, systems such as plumbing and electrical, and accessibility or energy upgrades are common. Luxury items and work that does not stay with the property are often excluded or limited.
Is FHA 203(k) the only rehab option?
No. Conventional renovation loans, such as Fannie Mae HomeStyle, can cover similar work with different occupancy, property and credit rules. We compare them for your situation.
Can I refinance and renovate the home I already own?
Yes, many programs allow a refinance with renovation funds. Depending on your equity, a Cash Out Refinance may also be worth comparing.
Do I have to use a licensed contractor?
In most cases, yes. Lenders review the contractor’s license, insurance and bid, and borrower labor is generally not financed.
How long does the work have to take?
Each program sets a completion window after closing, and the contractor’s schedule must fit inside it. Larger projects need a realistic schedule from the start.
Can I live in the home during the renovation?
Sometimes. Smaller projects often allow it, but if the home will be unlivable, some programs can include limited funds for housing costs while you are out.
Who should look at a fix and flip loan instead?
Anyone buying a property to renovate and resell rather than live in. That strategy uses a Fix & Flip Loan with business-purpose rules.
How Rehab Loans Work
A rehab loan works by approving the borrower, the property and the renovation plan together, then paying for the work in stages after closing. The sequence below is typical for an owner-occupied purchase.
-
Choose the home and scope the work
We review the property and your must-do list before an offer is final. An inspection, and for larger projects a consultant’s report, helps define what needs fixing.
-
Collect contractor bids
Your contractor provides a detailed, itemized bid with materials, labor, permits and a schedule. The lender reviews the contractor’s license and insurance.
-
Order the renovation appraisal
The appraiser uses the bid and plans to estimate the home’s value after the improvements are complete.
-
Underwrite and close
Your income, credit and assets are reviewed alongside the project. At closing, the purchase is funded and the renovation money goes into an escrow account.
-
Release draws as work is done
The contractor requests payment at set stages, an inspector confirms the work, and the lender releases funds with lien waivers.
-
Final inspection and close-out
Once the work passes final inspection, the last draw is paid and any unused contingency is handled under program rules, often applied to the loan balance.
Is a Renovation Mortgage a Good Choice for Your Home?
A renovation mortgage often fits when the home you want, or the home you own, needs real work and you would rather finance it with the mortgage than pay cash or borrow separately. It is less helpful for small cosmetic jobs.
Often a good fit
In our experience, rehab loans work well for buyers who find a well-located but dated home that other buyers pass over, and for owners who need a new roof or systems to keep the home insurable. If you have a reliable licensed contractor and the patience for a structured draw process, you may be able to buy and improve the home in one transaction.
Consider another path
For modest updates on a home you already own, a HELOC Home Loan may be simpler, though its rate is usually variable. If the plan is to tear down and rebuild, a construction loan is the more natural tool. If you want to do much of the work yourself, most rehab programs will not finance your labor.
Rehab Loan Costs and What to Expect
Rehab loans add renovation-specific costs on top of normal closing costs. Expect possible charges for draw inspections, title updates, a consultant on larger government-backed projects, and a contingency reserve built into the budget. Timelines run longer because the lender reviews the project as well as you.
| Feature | Rehab loan | Purchase now, renovate later |
|---|---|---|
| Financing for work | Included in the mortgage | Savings, a later equity loan or other credit |
| Appraisal basis | Value after improvements | Current as-is value |
| Contractor review | Required before closing | Your own choice |
| Paperwork | Bids, draws, inspections | Standard purchase file |
| Timeline | Usually longer to close | Faster to close, slower to finish |
Illustrative calculation (hypothetical figures)
Suppose the purchase price plus the approved renovation budget, including contingency, is compared against the appraiser’s value after improvements. If the requested loan equals 90 percent of that as-completed value, the loan-to-value ratio is 90 percent, and the lender checks it against the program maximum. Separately, if your monthly debts plus the qualifying monthly housing obligation (PITIA) use 39 percent of gross monthly income, the debt-to-income ratio is 39 percent.
This example is illustrative, not an approval or a program minimum. The lender determines the accepted figures, included expenses, and required ratio for the selected program. Actual rates, APR, payments, and terms depend on your scenario and are provided in your Loan Estimate.
Rehab Loan Mistakes to Avoid
Rehab loans go wrong most often when the bid, the contractor or the scope is not ready for lender review. These are the issues we flag early.
-
Submitting a one-line bid
A bid that says only “kitchen remodel” cannot be appraised or drawn against. Ask for line items with materials, labor and permits.
-
Choosing a contractor who will not wait for draws
Some contractors want large deposits up front. Confirm they accept staged payments after inspection before you build the file around them.
-
Skipping the roof and insurance check
What we typically see on older Florida homes is a buyer who plans a new kitchen first, then learns the insurer wants the roof or electrical panel replaced before binding a policy. Put insurability items at the top of the scope.
-
Adding work after closing
New work needs a formal change order and may not be fundable. Settle the scope before closing.
-
Underestimating the contingency
Opening walls in an older home often reveals more work. A thin contingency leaves you covering overruns yourself.
Renovation Financing in Naples, FL
Many Naples homes in established areas such as Lakewood, Naples Park and East Naples date from earlier decades and need roofs, windows or systems updated. Florida insurers commonly ask for a four-point inspection and wind mitigation report on older homes, so roofs, impact windows and electrical upgrades often belong in the first draw rather than the last.
Flood zones matter too. In parts of Collier County, a large enough renovation of a home below current flood elevation can trigger the substantial improvement rule, which may require bringing the whole structure up to current standards. With construction trades in steady demand after recent storms, we plan schedules with your contractor so the work fits the program’s completion window.
Peter Moran
Peter Moran is CEO/President of First Premier Mortgage Lending, LLC and a mortgage professional with NMLS #235959. He helps homebuyers and homeowners compare financing options, explains rates and costs in plain language, and stays involved from the first conversation through closing.
Construction and renovation financing is subject to property, contractor and project approval, and project costs and timelines can change. This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
First Premier Mortgage NMLS #2668389 · Peter Moran NMLS #235959. Licensed in FL. Verify licensing at NMLS Consumer Access.
01 Your improvement list
Separate essential repairs from the upgrades you would like to make.
02 Your contractor estimates
Gather the information needed to discuss a realistic scope and budget.
03 Your timeline
Consider when the work can begin and what happens if plans change.
Program requirements vary. A conversation is not a commitment to lend or a loan approval.