
Investor Construction Loans in Naples, FL
An investor construction loan finances building a residential property to sell or rent, with funds released in stages as work is completed. Lenders typically review the plans, budget and builder, and how you plan to repay the loan when the project is finished.
Loan availability and terms depend on borrower and property qualifications.
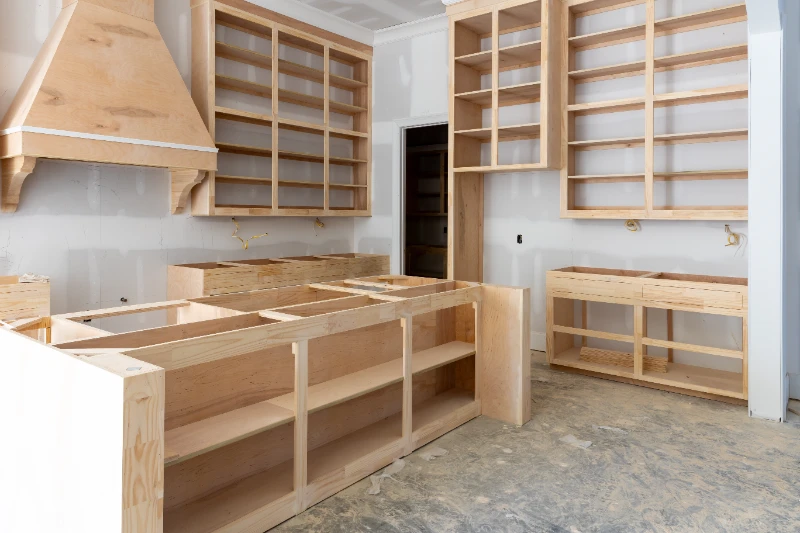
Start with the investment you want to build.
Finance the project from plans to completion.
Connect your investment strategy with the construction budget, funding process, and exit plan.
An investor construction loan is short-term, business-purpose financing for building a new non-owner-occupied home or small rental property from the ground up, with funds released in stages as construction is completed. For investors building in Naples, FL, First Premier Mortgage (NMLS #2668389) helps evaluate the lot, plans, builder, budget and the plan for repaying the loan once the home is finished.
Key Takeaways
- Built for spec and build-to-rent These loans finance new homes an investor plans to sell or hold as rentals, not a home you will live in.
- The lot is part of the equity Land you already own, or buy at closing, often counts toward your contribution to the project.
- The builder is underwritten too Lenders review the contractor’s license, insurance, experience and contract before approving the project.
- As-completed value guides the loan An appraisal based on plans and specifications estimates what the finished home will be worth.
- Contingency protects the build A budget line for overruns keeps a surprise from stalling the project or forcing a mid-build cash call.
- Plan the take-out first A sale or a long-term rental refinance must be realistic before the first draw is released.
Investor Construction Loan FAQ
Investor construction questions usually focus on the lot, the builder and how the loan ends. These are the ones we answer most often for spec and build-to-rent projects.
What is the difference between an investor construction loan and a regular construction loan?
A regular construction home loan finances a home you will occupy. An investor construction loan is business-purpose financing for a property you will sell or rent, with underwriting focused on the project and your exit.
Can I use land I already own as my contribution?
Often, yes. Lenders typically credit the land’s appraised or purchase value, subject to their rules on how long you have owned it and any existing lien on it.
Do I have to use a licensed general contractor?
Most programs require one. Investors acting as their own builder are accepted only by some lenders and usually need a documented construction background.
How are cost overruns handled?
The contingency line absorbs some overruns. Beyond that, the lender usually requires you to deposit the difference before further draws, so liquid funds matter throughout the build.
Is a duplex or small multi-unit build eligible?
Some programs finance one- to four-unit residential builds.
Can I refinance into a rental loan when the home is done?
That is a common exit. Once the home has a certificate of occupancy and a lease, a long-term rental loan such as a DSCR loan may replace the construction balance.
How long does approval take for a new build?
Timing depends on plans, permits, the builder package and the as-completed appraisal. Having permit-ready plans and a signed builder contract shortens it considerably.
How Investor Construction Loans Work
An investor construction loan works by approving the whole project up front and then funding it in inspected draws until the home is complete and the loan is repaid. These are the stages most builds follow.
-
Secure the lot and feasibility
Confirm zoning, flood zone, utilities, access and any deed restrictions. A lot that cannot support your plan is the most expensive surprise.
-
Assemble the builder package
Plans, specifications, a fixed-price or cost-plus contract and the builder’s license and insurance go to the lender for review.
-
Line-item budget and contingency
Hard costs, soft costs such as permits and engineering, and a contingency are set out in a draw schedule the lender approves.
-
As-completed appraisal
The appraiser estimates the finished value from the plans and comparable new construction. That figure, with the budget, shapes the loan amount.
-
Close and draw
After closing and permits, the builder completes stages, an inspector verifies them and the lender releases each draw.
-
Completion and exit
Once the certificate of occupancy is issued, the home is sold or refinanced into long-term financing to pay off the construction balance.
Who Should Consider Building to Sell or Rent
Investor construction financing tends to suit investors with a buildable lot, a proven builder and enough liquidity to absorb delays. It is a harder path for first projects without that support.
Often a good fit
Investors who own or can acquire a lot in an area with steady new-home demand, who have a builder with a track record of similar homes, and who have tested the as-completed value against recent new-construction sales often find this structure workable. It may also suit buy-and-hold investors who want a new, lower-maintenance rental built to current wind and flood codes, which can help with insurance over time.
Consider another path
If an existing home can be bought and renovated for less than building new, a fix and flip loan may involve less time and risk. If your cash reserves would be thin once the build starts, waiting to strengthen them may be wiser. And if you plan to live in the finished home, an owner-occupied construction loan is the appropriate product.
Investor Construction Costs and Draws
Construction financing costs more to carry than a long-term mortgage, because the lender manages draws, inspections and project risk for the life of the build. Expect origination and draw inspection fees, title updates with each draw in some programs, and builder’s risk insurance on the structure.
Financing charges usually accrue only on funds already disbursed, so the cost rises as the build progresses. Delays extend that cost, which is why the schedule matters as much as the budget.
| Feature | Investor construction loan | Fix and flip loan |
|---|---|---|
| Starting point | Vacant lot or teardown | Existing home needing work |
| Key value used | As-completed value from plans | As-is and after-repair value |
| Builder review | Licensed builder package required | Contractor bid often reviewed |
| Permits | Full building permit before first draw | Depends on scope of work |
| Typical exit | Sale or long-term rental refinance | Sale, sometimes a rental refinance |
Illustrative calculation (hypothetical figures)
Suppose the appraiser’s as-completed value is the reference point and the total construction loan you request equals 70 percent of that value, so the loan-to-completed-value ratio is 70 percent. Your contribution, including the appraised value of the lot you already own, covers the rest of the project cost. If the program also asks for a contingency equal to 10 percent of hard costs and liquid reserves equal to six months of projected carrying costs, both must be documented before the first draw.
This example is illustrative, not an approval or a program minimum. The lender determines the accepted figures, included expenses, and required ratio for the selected program. Actual rates, APR, payments, and terms depend on your scenario and are provided in your Loan Estimate.
Investor Construction Mistakes
Most construction loan problems start before closing, in the lot, the plans or the builder contract. Avoid these.
-
Buying the lot before checking flood elevation
In our experience, investors who buy a low-lying Naples-area lot before reviewing the required base flood elevation are surprised by fill, stem wall or pilings costs. Get a survey and elevation guidance before you close on the land.
-
Choosing the builder on price alone
A low bid from a builder who cannot pass the lender’s review delays everything. Ask for the builder’s license, insurance and references early.
-
Leaving soft costs out
Engineering, impact fees, utility connections and surveys add up. A budget built only on hard costs will come up short.
-
Counting on the first appraisal for the take-out
What we typically see is an investor who plans to refinance at the as-completed figure, then a new appraisal at completion comes in differently. Leave room in your exit plan for that.
Building Investment Homes in Naples, FL
New investor builds around Naples are concentrated where land is still available, especially Golden Gate Estates with its larger acreage lots and the communities growing east toward Ave Maria. Teardown-and-rebuild projects closer to the coast, around Park Shore and the Moorings, involve higher land values, stricter elevation rules and more complex permitting.
Construction is one of the region’s major industries, so builder schedules and material lead times tighten when demand rises after storms or during the winter season. Collier County building permits, flood elevation and wind-load codes all affect budget and timeline, and we factor them into the draw schedule with you from the start.
Peter Moran
Peter Moran is CEO/President of First Premier Mortgage Lending, LLC and a mortgage professional with NMLS #235959. He helps homebuyers and homeowners compare financing options, explains rates and costs in plain language, and stays involved from the first conversation through closing.
Business-purpose loans for non-owner-occupied property; consumer protections may differ. Construction and renovation financing is subject to property, contractor and project approval, and project costs and timelines can change. This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
First Premier Mortgage NMLS #2668389 · Peter Moran NMLS #235959. Licensed in FL. Verify licensing at NMLS Consumer Access.
01 Plans and approvals
Gather available plans, permits, and property information.
02 Builder and estimates
Review contractor details, the budget, and contingencies.
03 Completion strategy
Discuss the expected sale or rental plan and long-term financing needs.
Program requirements vary. A conversation is not a commitment to lend or a loan approval.